
The objective of this Standard is to require an entity to provide relevant information that faithfully represents how regulatory income and regulatory expense affect the entity’s financial performance, and how regulatory assets and regulatory liabilities affect its financial position.
(Note – links in this version to another pronouncement will not work as the compilations of the pronouncements incorporating the amendments in Appendix D of this Standard have not yet been published on this portal. New compilations of those other pronouncements will be published in due course.)
Preamble
Pronouncement
Obtaining a copy of this Accounting Standard
This Standard is available on the AASB Digital Standards Portal (standards.aasb.gov.au), which can also be accessed from aasb.gov.au.
Australian Accounting Standards Board
PO Box 204
Collins Street West
Victoria 8007
AUSTRALIA
Phone: (03) 9617 7600
E-mail: [email protected]
Website: www.aasb.gov.au
Other enquiries
Phone: (03) 9617 7600
E-mail: [email protected]
Copyright
© Commonwealth of Australia 2026
This AASB Standard contains IFRS Foundation copyright material. Reproduction within Australia in unaltered form (retaining this notice) is permitted for personal and non-commercial use subject to the inclusion of an acknowledgment of the source. Requests and enquiries concerning reproduction and rights for commercial purposes within Australia should be addressed to The Managing Director, Australian Accounting Standards Board, PO Box 204, Collins Street West, Victoria 8007.
All existing rights in this material are reserved outside Australia. Reproduction outside Australia in unaltered form (retaining this notice) is permitted for personal and non-commercial use only. Further information and requests for authorisation to reproduce IFRS Foundation copyright material for commercial purposes outside Australia should be addressed to the IFRS Foundation at www.ifrs.org.
Rubric
Australian Accounting Standard AASB 20 Regulatory Assets and Regulatory Liabilities is set out in paragraphs 1–Aus83.1 and Appendices A–E. All the paragraphs have equal authority. Paragraphs in bold type state the main principles. Terms defined in Appendix A are in italics the first time they appear in the Standard. AASB 20 is to be read in the context of other Australian Accounting Standards, including AASB 1048 Interpretation of Standards, which identifies the Australian Accounting Interpretations, and AASB 1057 Application of Australian Accounting Standards. In the absence of explicit guidance, AASB 108 Basis of Preparation of Financial Statements provides a basis for selecting and applying accounting policies.
Preface
Introduction
The Australian Accounting Standards Board (AASB) develops, issues and maintains Australian Accounting Standards, including Interpretations. The AASB is an Australian Government entity under the Australian Securities and Investments Commission Act 2001.
AASB 1057 Application of Australian Accounting Standards identifies the application of Standards to entities and financial statements. AASB 1053 Application of Tiers of Australian Accounting Standards establishes a differential reporting framework consisting of three tiers of reporting requirements for preparing general purpose financial statements.
Main features of this Standard
Background
In May 2026, the International Accounting Standards Board issued International Financial Reporting Standard IFRS 20 Regulatory Assets and Regulatory Liabilities. IFRS 20 supersedes IFRS 14 Regulatory Deferral Accounts. IFRS 20 aims to help investors better understand how rate regulation affects an entity’s financial performance, financial position and its prospects for future cash flows. AASB 20 Regulatory Assets and Regulatory Liabilities is the Australian equivalent of IFRS 20.
The Standard applies to entities subject to rate regulation that determines how much and when they can charge customers for goods or services supplied under a regulatory agreement, for example in sectors such as electricity, water and gas. Differences in timing arise when compensation for regulatory goods or services supplied in one reporting period is reflected in regulated rates charged in another period. The Standard requires entities to provide information about the effect of these timing differences on their financial performance and financial position.
Main requirements
AASB 20 requires an entity to account for the effects of differences in timing through the recognition of regulatory assets and regulatory liabilities and related regulatory income and regulatory expense. The Standard focuses on a type of rate regulation that:
(a) entitles an entity to an amount of compensation for regulatory goods or services supplied in a period (the ‘total allowed compensation’); and
(b) specifies the timing of when that compensation is charged to customers through the regulated rates.
A difference in timing arises if part or all of the total allowed compensation for regulatory goods or services supplied in one reporting period is included in determining the regulated rates charged to customers in a different period.
AASB 20 supersedes AASB 14 Regulatory Deferral Accounts. As a result, the requirements in AASB 14 have been replaced by new requirements in AASB 20.
Application date
This Standard applies to annual reporting periods beginning on or after 1 January 2029. Earlier application is permitted.
Tier 2 simplified disclosure requirements
Disclosure requirements under Tier 2 (if any) will be determined through a separate due process with amendments being made subsequently to AASB 1060 General Purpose Financial Statements – Simplified Disclosures for For-Profit and Not-For-Profit Tier 2 Entities as required.
Comparison with IFRS 20
AASB 20 Regulatory Assets and Regulatory Liabilities incorporates IFRS 20 Regulatory Assets and Regulatory Liabilities issued by the International Accounting Standards Board (IASB). Australian-specific paragraphs (which are not included in IFRS 20) are identified with the prefix “Aus”. Paragraphs that apply only to not‑for‑profit entities begin by identifying their limited applicability.
For-profit entities complying with AASB 20 also comply with IFRS 20.
Not-for-profit entities’ compliance with IFRS 20 will depend on whether any “Aus” paragraphs that specifically apply to not-for-profit entities provide additional guidance or contain applicable requirements that are inconsistent with IFRS 20.
AASB 1053 Application of Tiers of Australian Accounting Standards explains the three tiers of reporting requirements.
Accounting Standard AASB 20
The Australian Accounting Standards Board makes Accounting Standard AASB 20 Regulatory Assets and Regulatory Liabilities under section 334 of the Corporations Act 2001.
Keith Kendall
Chair – AASB
Dated 12 October 2026
Objective
1
The objective of this Standard is to require an entity to provide relevant information that faithfully represents how regulatory income and regulatory expense affect the entity’s financial performance, and how regulatory assets and regulatory liabilities affect its financial position. To achieve this objective, the Standard sets out requirements for the recognition, measurement, presentation and disclosure of regulatory assets, regulatory liabilities, regulatory income and regulatory expense.
2
Regulatory assets and regulatory liabilities are a subset of the rights and obligations created by a regulatory agreement. Information about this subset of rights and obligations enables users of financial statements to understand:
(a) an entity’s regulatory income and regulatory expense, which arise from the regulatory assets and regulatory liabilities. That understanding, together with information required by other Australian Accounting Standards, will provide insights into the total allowed compensation for regulatory goods or services supplied by the entity in a reporting period, and hence into the entity’s financial performance and prospects for future cash flows.
(b) an entity’s regulatory assets and regulatory liabilities. That understanding will provide insights into the entity’s financial position at the end of a reporting period and the amount, timing and uncertainty of the entity’s future cash flows.
3
Total allowed compensation is the amount of compensation to which a regulatory agreement entitles an entity for regulatory goods or services supplied in a reporting period. The amount might be charged through regulated rates – and hence included in revenue from contracts with customers recognised applying AASB 15 Revenue from Contracts with Customers (referred to in this Standard as AASB 15 revenue) – in either the same period as the entity supplies the regulatory goods or services, or a different period. The Standard establishes definitions of a regulatory asset and a regulatory liability, and resulting definitions of regulatory income and regulatory expense, based on the principle that an entity recognises the total allowed compensation for regulatory goods or services in the same reporting period that the entity supplies those regulatory goods or services.
Scope
4
An entity shall apply this Standard to all its regulatory assets and all its regulatory liabilities, except for regulatory assets and regulatory liabilities that arise if premiums charged in insurance contracts within the scope of AASB 17 Insurance Contracts are regulated.
5
This Standard specifies how to account for regulatory assets and regulatory liabilities and the resulting regulatory income and regulatory expense. Its application results in information that supplements the information provided by applying other Australian Accounting Standards, primarily information about revenue from contracts with customers recognised applying AASB 15. An entity shall apply other Australian Accounting Standards to account for rights and obligations created by a regulatory agreement before applying this Standard.
Regulatory assets, regulatory liabilities, regulatory income and regulatory expense
6
A regulatory asset is an enforceable present right, created by a regulatory agreement, to add an amount in determining a regulated rate to be charged to customers in future periods because part or all of the total allowed compensation for regulatory goods or services already supplied has not yet been included in AASB 15 revenue. A right to add an amount in determining a future regulated rate for any other reason is not a regulatory asset.
7
A regulatory liability is an enforceable present obligation, created by a regulatory agreement, to deduct an amount in determining a regulated rate to be charged to customers in future periods because part or all of the total allowed compensation for regulatory goods or services to be supplied in the future has already been included in AASB 15 revenue. An obligation to deduct an amount in determining a future regulated rate for any other reason is not a regulatory liability.
8
In determining whether a regulatory asset or a regulatory liability exists, an entity shall assess whether it has an enforceable present right to add, or an enforceable present obligation to deduct, an amount in determining a regulated rate to be charged to customers in future periods (see paragraphs B3–B7).
9
A regulatory asset or a regulatory liability can exist only if:
(a) an entity and a regulator are parties to a regulatory agreement that prescribes the regulated rate the entity charges for goods or services it supplies to customers (see paragraphs 11–13); and
(b) part or all of the total allowed compensation for regulatory goods or services supplied by the entity in a reporting period is charged to customers through regulated rates in a different period (past or future), creating a difference in timing (see paragraphs 14–23).
10
Regulatory income and regulatory expense are income or expense arising from changes in a regulatory asset or regulatory liability. Not all changes in regulatory assets or regulatory liabilities give rise to regulatory income or regulatory expense – for example, the acquisition of regulatory assets or assumption of regulatory liabilities in a business combination does not give rise to regulatory income or regulatory expense. In addition, exchange differences resulting from translation into a presentation currency in accordance with AASB 121 The Effects of Changes in Foreign Exchange Rates are not regulatory income or regulatory expense.
Regulatory agreement and regulator
11
A regulatory agreement is an agreement that creates a set of enforceable rights and enforceable obligations that prescribes how a regulator determines a regulated rate (or a range for the regulated rate) that an entity charges for goods or services supplied to customers in a period. A regulator is a body that is required by law or regulation to apply a regulatory agreement to determine a regulated rate (or a range for the regulated rate – see paragraphs B8–B10).
12
The legal forms of regulatory agreements vary by jurisdiction and industry. For example, a regulatory agreement might take the form of:
(a) a contractual licensing agreement;
(b) a service concession arrangement; or
(c) a set of rights and obligations specified by law or regulation.
13
A regulatory agreement might create only regulatory assets, only regulatory liabilities or both regulatory assets and regulatory liabilities.
Total allowed compensation and differences in timing
14
Total allowed compensation is the amount of compensation to which a regulatory agreement entitles an entity for regulatory goods or services supplied in a reporting period. The amount might be charged through regulated rates in either the same period as the entity supplies the regulatory goods or services, or a different period.
15
Regulatory goods or services are goods or services supplied by an entity to comply with a regulatory agreement. Regulatory goods or services supplied in a period might include, for example:
(a) supplying goods or services to customers;
(b) maintaining a network, including routine maintenance, and being ready to repair damage to the network;
(c) making changes to the capacity of a network (for example, additions and upgrades or decommissioning); and
(d) satisfying other objectives set by the regulator as part of the regulatory agreement (for example, improving the quality and efficiency of services supplied to customers, or decreasing or increasing customer usage).
16
The amount of AASB 15 revenue an entity recognises in a reporting period depends on the regulated rate charged for goods or services the entity supplies to customers in the period. In some cases, that amount of AASB 15 revenue differs from the total allowed compensation for regulatory goods or services supplied by the entity in the reporting period. Specifically, the amount differs if part or all of the total allowed compensation for regulatory goods or services supplied in the period is included in determining the regulated rates charged to customers in a different period (past or future). Such differences in timing might give rise to regulatory assets or regulatory liabilities.
| Example | |
To illustrate a difference in timing described in paragraph 16, assume that the regulated rate an entity charged for goods or services supplied to customers in 20X1 was based on estimated input costs of CU100.[1] However, the entity recognised actual input costs in that year of CU120. Assume also that the regulatory agreement gives the entity an enforceable present right to add the resulting CU20 under-recovery of those input costs in determining the regulated rate to be charged to customers in 20X2.[2] In this example, the entity’s AASB 15 revenue for 20X1 includes compensation of CU100 based on the estimated input costs. Compensation for the CU20 under-recovery of input costs in 20X1 will be added in determining the regulated rates to be charged to customers in 20X2, and hence will be included in AASB 15 revenue in 20X2. However, that compensation of CU20 forms part of the total allowed compensation for regulatory goods or services supplied in 20X1, not for those supplied in 20X2 – the total allowed compensation for regulatory goods or services supplied in 20X1 is CU120. |
17
Applying AASB 15 could also result in a difference between the period in which an entity supplies goods or services to customers and the period in which the revenue for those goods or services is recognised. For example, such a difference might arise if the entity supplies goods or services to a customer but, applying paragraph 56 of AASB 15, the entity constrains the estimates of variable consideration until the associated uncertainty is resolved. Such differences do not give rise to regulatory assets or regulatory liabilities.
18
To supplement the information an entity provides by applying AASB 15, this Standard sets out requirements for the recognition of regulatory income and regulatory expense. The definitions of a regulatory asset and a regulatory liability, and resulting definitions of regulatory income and regulatory expense, are based on the principle that an entity recognises the total allowed compensation for regulatory goods or services supplied by the entity in the same reporting period that the entity supplies those regulatory goods or services.
19
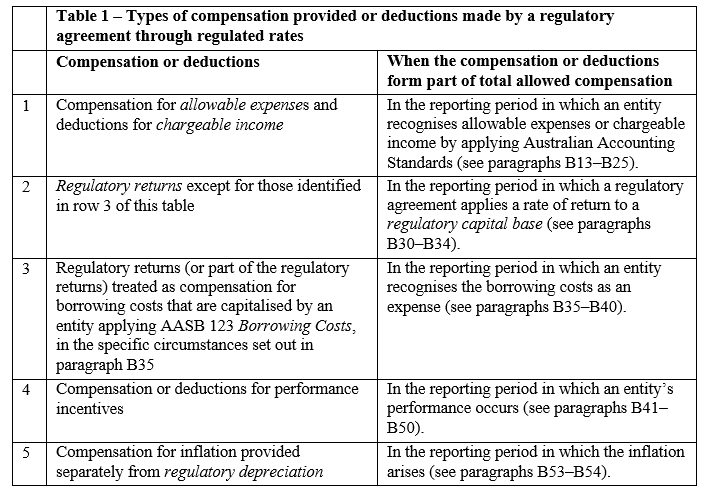
Table 1 sets out the most common types of compensation provided or deductions made by regulatory agreements through regulated rates, and establishes when the compensation or deductions form part of total allowed compensation.
20
In addition, for the purpose of applying this Standard, an entity shall treat compensation provided by inflation adjustments to the regulatory capital base as forming part of the total allowed compensation for the reporting period in which the inflation is recovered through regulatory depreciation included in determining the regulated rates charged to customers (see paragraph B52).
21
The terms of regulatory agreements vary by jurisdiction and industry. Accordingly, a regulatory agreement might not provide all the types of compensation or make all the types of deductions described in paragraphs 19–20, might provide other types of compensation or make other types of deductions or might use different terminology to refer to the types of compensation or deductions described in paragraphs 19–20. An entity shall use its judgement in analysing the terms and conditions of a regulatory agreement to determine what types of compensation or deductions the regulatory agreement provides or makes. If the regulatory agreement provides a type of compensation or makes a type of deduction other than those described in paragraphs 19–20, the entity shall use its judgement to determine when that compensation or deduction forms part of total allowed compensation.
22
Paragraphs B13–B54 describe when differences in timing might arise from the compensation or deductions described in paragraphs 19–20.
23
Differences in timing might also arise from the under‑recovery or over‑recovery of allowed revenue as described in paragraphs B57–B58.
Monetary amounts are denominated in ‘currency units’ (CU).
For simplicity, this example ignores the effect of regulatory interest.
Unit of account
24
An entity shall account for the right or obligation arising from an individual difference in timing – or from a group of differences in timing that are created by the same regulatory agreement, have similar expiry patterns and are subject to similar risks – as a single unit of account.
25
An entity is permitted to apply paragraph B37 to determine an individual difference in timing arising from part or all of the regulatory return that is treated as compensation for capitalised borrowing costs. An entity shall apply paragraph B66 to determine an individual difference in timing arising from regulatory depreciation of a regulatory capital base that has a direct relationship with depreciable or amortisable assets (as described in paragraph B64).
Recognition
26
Except as specified in paragraphs 29 and 31, an entity shall recognise:
(a) all regulatory assets and all regulatory liabilities existing at the end of a reporting period; and
(b) all regulatory income and all regulatory expense arising during a reporting period.
Existence uncertainty
27
If there is uncertainty about whether a regulatory asset or regulatory liability exists, an entity shall assess whether the regulatory asset or regulatory liability is more likely than not to exist. If the regulatory asset or regulatory liability is more likely than not to exist, and meets the criteria specified in paragraph 29 or 31 if applicable, the entity shall recognise it.
28
Uncertainty about the existence of a regulatory asset or regulatory liability might arise from uncertainty about the existence of a present right or present obligation, uncertainty about the enforceability of the present right or present obligation, or uncertainty about both existence and enforceability. The existence of a present right or present obligation does not need to be certain for an entity to be able to assess its enforceability. An entity shall consider both types of uncertainty and make a combined assessment of whether it is more likely than not that an enforceable present right or enforceable present obligation exists.
Recognition criterion for a regulatory asset or regulatory liability arising from regulatory depreciation of a regulatory capital base
29
An entity shall recognise a regulatory asset or regulatory liability arising from regulatory depreciation of a regulatory capital base if, and only if, the regulatory capital base has a direct relationship with a related item or items (see paragraph B59). A related item is an item that gives rise to amounts for which a regulatory agreement creates a right to compensation to be provided, or an obligation for a deduction to be made, through regulatory depreciation.
30
An entity’s regulatory capital base has a direct relationship with a related item or items if the entity is able to track, by amount and reporting period, how regulatory depreciation provides compensation or makes a deduction for the amounts arising from the related item or items (see paragraphs B60–B72).
Recognition criterion for a regulatory asset or regulatory liability arising from compensation based on a benchmark determined using unobservable inputs
31
Compensation for an allowable expense might be based on a benchmark (for example, the actual expenses of an entity’s peer group). In some cases, the benchmark is determined using unobservable inputs, and the regulator determines the compensation only after the entity’s financial statements are authorised for issue. In such cases, an entity shall recognise any resulting regulatory asset or regulatory liability only when the regulator determines the compensation based on the actual benchmark.
Derecognition
32
An entity shall derecognise part or all of a regulatory asset or regulatory liability when that part or all of the amount recognised no longer meets the definition of a regulatory asset or regulatory liability. For example:
(a) when the entity recovers part or all of a regulatory asset or fulfils part or all of a regulatory liability and, applying paragraph 53(a), updates the estimates of future cash flows.
(b) when part or all of a regulatory asset is settled or when part or all of a regulatory liability is waived by a regulator or another party. In such cases, an entity shall:
(i) recognise an asset or liability if required by other Australian Accounting Standards (for example, a financial asset or financial liability recognised by applying AASB 9 Financial Instruments); and
(ii) recognise in profit or loss the difference between the amount derecognised and any new asset or new liability recognised by applying another Australian Accounting Standard.
33
An entity shall also derecognise part or all of a regulatory asset or regulatory liability when that part or all of the regulatory asset or regulatory liability no longer meets the recognition criteria set out in paragraph 27 or 29. In such cases, an entity shall derecognise the part of the regulatory asset or regulatory liability that no longer meets the recognition criteria and recognise any related regulatory expense or regulatory income in profit or loss.
Measurement
34
Except as specified in paragraph 60, an entity shall measure regulatory assets and regulatory liabilities using a cash‑flow‑based measurement technique that:
(a) includes an up‑to‑date estimate of all future cash flows arising from the recovery of a regulatory asset or fulfilment of a regulatory liability (see paragraphs 35–44 and 52–57); and
(b) discounts those estimated future cash flows using the regulatory interest rate (see paragraphs 45–52 and 56–57).
Initial measurement
Estimating future cash flows
Identifying future cash flows
35
To apply paragraph 34(a), an entity shall include all estimated future cash flows arising from the recovery of a regulatory asset or fulfilment of a regulatory liability that are within the boundary of the regulatory agreement, and only those cash flows. Such cash flows comprise:
(a) cash flows for which an entity has an enforceable present right to add amounts, or an enforceable present obligation to deduct amounts, in determining the regulated rates to be charged to customers in future periods. The future periods are those in which the entity has an enforceable present right or enforceable present obligation to supply regulatory goods or services.
(b) cash flows for which an entity has an enforceable present right to receive, or an enforceable present obligation to pay, compensation on termination of a regulatory agreement.
36
Paragraphs B73–B87 set out requirements for determining the boundary of a regulatory agreement.
37
To estimate future cash flows, an entity shall consider all reasonable and supportable information that is available at the reporting date without undue cost or effort. The entity shall consider information about past events and about conditions existing at the reporting date. The entity shall also consider information about variables that might affect estimates of future cash flows, namely:
(a) market variables – variables that can be observed in, or derived directly from, markets (for example, interest rates). The entity shall use assumptions about future market variables that are consistent with observable market prices at the reporting date – that is, at the reporting date, the entity shall disregard the effects of possible future changes in market variables.
(b) non‑market variables – all other variables other than market variables (for example, the useful life of a depreciable asset). The entity shall use its expectations at the reporting date about future non‑market variables, other than future changes in the regulatory agreement or in law or regulation.
38
Cash flows arising from a regulatory asset or regulatory liability include cash flows from regulatory interest specified in a regulatory agreement. However, if an entity elects to apply the exemption from discounting described in paragraph 50, the entity shall, in periods for which it applies the exemption, exclude regulatory interest cash flows from the estimates of future cash flows arising from the regulatory asset or regulatory liability.
Uncertain future cash flows
39
There might be uncertainty about the amount or timing of future cash flows that will arise from a regulatory asset or regulatory liability. Such uncertainty might be caused by, for example, credit risk or demand risk. The effect of credit risk and demand risk on the future cash flows depends on whether the entity or its customers bear the risk (see paragraphs B88–B91).
40
An entity’s estimates of future cash flows arising from a regulatory liability shall not reflect non‑performance risk of the entity (non‑performance risk is defined in AASB 13 Fair Value Measurement).
41
An entity shall estimate uncertain future cash flows using an unbiased range of possible outcomes incorporating the information described in paragraph 37, including outcomes in which the regulatory asset or regulatory liability does not exist, or produces no future cash flows.
42
An entity shall estimate uncertain future cash flows using whichever of these two methods the entity expects to better predict the ultimate cash flow that will occur after the uncertainty is resolved:
(a) the most likely amount, which is the single most likely amount in a range of possible outcomes (that is, a range of possible cash flows). The most likely amount might better predict the ultimate cash flow if the possible cash flows are clustered around one cash flow, or if there are only two possible cash flows and they differ widely.
(b) the expected value, which is the sum of the probability‑weighted amounts in a range of possible outcomes. The expected value might better predict the ultimate cash flow if there are many possible cash flows and they are not clustered around one cash flow.
43
In assessing which of the methods described in paragraph 42 would better predict the ultimate cash flow, an entity shall also assess whether a better prediction would result from:
(a) considering separately each regulatory asset and each regulatory liability identified by the entity applying paragraph 24. An entity shall use one of the methods of estimating uncertain future cash flows for some regulatory assets or regulatory liabilities and the other method for other regulatory assets or regulatory liabilities, if the entity expects that doing so will better predict the ultimate cash flow.
(b) considering any regulatory asset or regulatory liability together with other regulatory assets or regulatory liabilities. If such a grouping will better predict the ultimate cash flow, the entity shall apply the method that it expects will provide the better prediction to all the regulatory assets and regulatory liabilities in the group.
Foreign currency amounts
44
If regulated rates charged to customers are denominated in a foreign currency, an entity shall treat any related regulatory assets or regulatory liabilities as monetary items when applying AASB 121.
44
If regulated rates charged to customers are denominated in a foreign currency, an entity shall treat any related regulatory assets or regulatory liabilities as monetary items when applying AASB 121.
Discounting estimated future cash flows
45
Except as specified in paragraph 50, an entity shall discount the estimated future cash flows arising from a regulatory asset or regulatory liability using the regulatory interest rate specified or implied by the regulatory agreement for that regulatory asset or regulatory liability.
46
For a regulatory asset or regulatory liability that arises from regulatory depreciation of a regulatory capital base, the regulatory interest rate is the rate of return that the regulatory agreement applies to the regulatory capital base (see paragraph B30).
47
In some cases, an entity shall derive an implied regulatory interest rate from the terms of a regulatory agreement instead of using the interest rate specified in the regulatory agreement (see paragraphs 48–50).
An implied regulatory interest rate
48
An entity shall derive an implied regulatory interest rate if the regulatory agreement includes any of these terms:
(a) it specifies uneven interest rates over the life of a regulatory asset or regulatory liability. For example, a period of time might elapse between an entity recognising a regulatory asset or regulatory liability and a regulatory agreement starting to apply an interest rate to that regulatory asset or regulatory liability (see paragraph 50).
(b) it specifies an interest rate that does not apply to regulatory interest accrued in past periods, instead of a compound interest rate.
(c) it does not specify an interest rate but instead adjusts the amount of compensation provided or a deduction made for an item to also provide compensation or make a deduction for the time period until the recovery of the related regulatory asset or the fulfilment of the related regulatory liability. An entity shall use its judgement to determine whether a regulatory agreement provides compensation or makes a deduction for such a time period. Not all regulatory agreements specify an interest rate or provide compensation or make a deduction for such a time period, in which case the regulatory interest rate is nil.
49
In the cases described in paragraph 48, an entity shall determine the implied regulatory interest rate as the rate that at initial recognition discounts the estimates of future cash flows arising from a regulatory asset or regulatory liability, which include regulatory interest cash flows (see paragraph 38), back to an amount that equals the sum of the estimated future cash flows, excluding regulatory interest.
50
In some cases, an entity expects the period between the recognition of a regulatory asset or regulatory liability and the date when an interest rate specified in the regulatory agreement starts to apply to be one year or less. In such cases, the entity need not discount the estimated future cash flows arising from the regulatory asset or regulatory liability during that period. If the entity elects to apply that exemption, the entity shall discount the estimated future cash flows once the interest rate specified in the regulatory agreement starts to apply.
Regulatory interest rates linked to interest rate benchmarks
51
The uneven interest rates described in paragraph 48(a) do not include interest rates specified in a regulatory agreement that are linked to an interest rate benchmark. In such cases, applying paragraph 37(a), the entity shall disregard possible future changes in the interest rate benchmark until they occur, at which time the entity shall apply paragraphs 56–57.
Subsequent measurement
52
In measuring a regulatory asset or regulatory liability after its initial recognition, an entity shall at the end of each reporting period:
(a) update estimates of the amount and timing of future cash flows arising from the regulatory asset or regulatory liability (see paragraphs 53–57); and
(b) continue to use the discount rate determined at initial recognition, except as described in paragraphs 56–57.
53
An entity shall update the estimated future cash flows arising from a regulatory asset or regulatory liability at the end of each reporting period by applying paragraphs 35–44 to reflect, for example:
(a) recovery of part or all of the regulatory asset or fulfilment of part or all of the regulatory liability; and
(b) any changes in estimates of the amount or timing of future cash flows because of a change in facts or circumstances or because of new information considered in accordance with paragraph 37.
54
Changes in facts or circumstances or new information, as described in paragraph 53(b), include:
(a) resolution of an uncertainty – for example:
(i) confirmation that the entity has met or not met performance criteria or confirmation of the outcome of court rulings; or
(ii) the regulator’s agreement or disagreement with regulatory filings made by the entity or by other entities;
(b) actions by a regulator other than those in (a)(ii) – for example, the exercise of a right to renew or terminate a regulatory agreement, causing a change in the boundary of the regulatory agreement (see paragraphs B75–B78);
(c) changes in credit risk or demand risk (see paragraphs B88–B91);
(d) changes in the regulatory interest rate as described in paragraph 56; or
(e) changes in a regulatory agreement or in law or regulation.
55
An entity shall reassess the selected method of estimating uncertain future cash flows arising from a regulatory asset or regulatory liability – determined by applying paragraphs 42–43 – if, and only if:
(a) facts or circumstances change or new information becomes available; and
(b) the change or new information might alter the entity’s expectation of the method that will better predict the ultimate cash flow.
56
In some cases, the regulatory interest rate specified or implied by a regulatory agreement changes after initial recognition of a regulatory asset or regulatory liability because of a change in:
(a) the regulatory agreement; or
(b) an interest rate benchmark to which the regulatory interest rate is linked.
57
Such a change in the regulatory interest rate changes the future cash flows arising from a regulatory asset or regulatory liability. Consequently, when the regulatory interest rate changes as described in paragraph 56, an entity shall:
(a) update the future cash flows estimated by applying paragraphs 35–44.
(b) discount the estimated future cash flows using the new regulatory interest rate. The new regulatory interest rate is the new interest rate specified in the regulatory agreement or the new implied regulatory interest rate determined applying paragraph 48. The new implied regulatory interest rate discounts all the updated future cash flows to the carrying amount of the regulatory asset or regulatory liability immediately before the new rate applied.
Simplified measurement approach – Items that affect regulated rates only when the related cash is paid or received
58
In some cases, a regulatory agreement provides compensation for an allowable expense or makes a deduction for chargeable income in determining the regulated rates charged to customers only when an entity pays or receives the related cash, or soon after that. A regulatory asset or regulatory liability might arise if, applying Australian Accounting Standards, the entity recognises the allowable expense or chargeable income in a different reporting period.
59
Similarly, a regulatory asset might arise because a regulatory agreement provides compensation for credit losses in determining the regulated rates only when the regulator determines that there is no reasonable expectation of an entity receiving the related cash, instead of when the entity recognises impairment losses in its financial statements by applying AASB 9.
60
An entity shall measure a regulatory asset or regulatory liability described in paragraphs 58–59 by:
(a) using the carrying amount of the related liability, related asset or related loss allowance resulting from applying Australian Accounting Standards.
(b) adjusting that carrying amount to reflect any differences between the related liability, related asset or related loss allowance and the regulatory asset or regulatory liability. Such a difference might be caused by (i) an uncertainty present in the related liability, related asset or related loss allowance but not in the regulatory asset or regulatory liability or (ii) an uncertainty present in the regulatory asset or regulatory liability but not in the related liability, related asset or related loss allowance. Such uncertainties might arise from estimation, credit or demand risk.
61
An entity shall stop applying paragraph 60, and shall thereafter measure any remaining part of the regulatory asset or regulatory liability by applying paragraphs 34–57, when:
(a) for a regulatory asset or regulatory liability described in paragraph 58 – the entity pays cash to settle the related liability, or receives cash to recover the related asset;
(b) for a regulatory asset described in paragraph 59 – the regulator has determined there is no reasonable expectation of the entity receiving the related cash; or
(c) for a regulatory asset or regulatory liability described in paragraph 58 or 59 – the entity derecognises the related liability, related asset or related loss allowance for any other reason.
Classification and presentation
Statement(s) of financial performance
62
Except as required by paragraph 64, an entity shall:
(a) classify all regulatory income and all regulatory expense as revenue; and
(b) present all regulatory income minus all regulatory expense as a line item in the statement of profit or loss.
63
Regulatory income includes regulatory interest income and regulatory expense includes regulatory interest expense.
64
In some cases, an entity applying other Australian Accounting Standards includes an item of expense or income in other comprehensive income. In such cases, the entity shall also include in other comprehensive income regulatory income or regulatory expense relating to that item of expense or income, as specified in paragraph 65. The entity shall:
(a) classify regulatory income and regulatory expense included in other comprehensive income in accordance with paragraph 88 of AASB 18 Presentation and Disclosure in Financial Statements;
(b) present regulatory income or regulatory expense separately from the related expense or related income;
(c) reclassify regulatory income or regulatory expense included in other comprehensive income to the statement of profit or loss if, and only if, the entity reclassifies the related expense or related income to the statement of profit or loss in accordance with other Australian Accounting Standards; and
(d) classify and present the reclassified regulatory income or regulatory expense in accordance with paragraph 62.
65
The regulatory income or regulatory expense to be included in other comprehensive income is the regulatory income or regulatory expense that arises in a reporting period because an entity recognises the related expense or related income that is included in other comprehensive income in that period. The entity determines such regulatory income or regulatory expense based on the amount of the compensation or deduction for that related expense or related income.
66
To apply paragraph 64(c) when an entity derecognises a regulatory asset or regulatory liability applying paragraph 32(b) or 33, the entity:
(a) shall not reclassify regulatory income or regulatory expense included in other comprehensive income to the statement of profit or loss when the entity derecognises the regulatory asset or regulatory liability; and
(b) shall reclassify any regulatory income or regulatory expense included in other comprehensive income to the statement of profit or loss when the entity reclassifies the related expense or related income to the statement of profit or loss.
Statement of financial position
67
An entity shall present in its statement of financial position:
(a) regulatory assets and regulatory liabilities as line items; and
(b) current and non-current regulatory assets, and current and non‑current regulatory liabilities, as separate classifications in accordance with paragraphs 99–102 of AASB 18, except when the entity presents all assets and liabilities in order of liquidity.
Disclosure
68
The overall objective of paragraphs 69–83 and B95–B97 is to require an entity to disclose in the notes information about the entity’s:
(a) regulatory income and regulatory expense that, together with the information required by other Australian Accounting Standards, will provide insights into the total allowed compensation for regulatory goods or services supplied by the entity in a reporting period, and hence into the entity’s financial performance and prospects for future cash flows; and
(b) regulatory assets and regulatory liabilities that will provide insights into the entity’s financial position at the end of a reporting period and the amount, timing and uncertainty of the entity’s future cash flows.
Regulatory assets and regulatory liabilities and resulting regulatory income and regulatory expense
69
An entity shall disclose information that enables users of financial statements to understand:
(a) the amounts that are recognised in the statement of financial position and statement(s) of financial performance for regulatory assets, regulatory liabilities, regulatory income and regulatory expense; and
(b) the nature of unrecognised regulatory assets or unrecognised regulatory liabilities and the reason they have not been recognised.
70
This information provides insights into:
(a) the total allowed compensation for regulatory goods or services supplied by the entity in a reporting period, in particular the extent to which part or all of the total allowed compensation for regulatory goods or services supplied by the entity in a reporting period was (or will be) included in determining the regulated rates charged to customers – and hence included in AASB 15 revenue – in a different period; and
(b) the amount, timing and uncertainty of the entity’s future cash flows.
71
To achieve the objective set out in paragraph 69, an entity shall apply paragraphs 72–81.
Recognised regulatory assets and recognised regulatory liabilities
72
An entity shall disclose, in a table, reconciliations from the opening to the closing carrying amounts of regulatory assets and from the opening to the closing carrying amounts of regulatory liabilities. In the reconciliations, an entity shall group the changes described in paragraph 73 into:
(a) changes included in the statement of profit or loss;
(b) changes included in other comprehensive income; and
(c) other changes not included in (a) or (b) (see paragraph 73(g)).
73
An entity shall disclose in the reconciliations required by paragraph 72 changes in the carrying amount of a regulatory asset or regulatory liability arising from:
(a) the origination of regulatory assets during the reporting period;
(b) the origination of regulatory liabilities during the reporting period;
(c) the recovery of regulatory assets during the reporting period;
(d) the fulfilment of regulatory liabilities during the reporting period;
(e) regulatory interest income on regulatory assets or regulatory interest expense on regulatory liabilities;
(f) other components of regulatory income or regulatory expense – for example, changes in the carrying amount of a regulatory asset or regulatory liability arising from remeasurements of the regulatory asset or regulatory liability or changes in the boundary of a regulatory agreement; and
(g) changes in regulatory assets and regulatory liabilities that did not give rise to regulatory income or regulatory expense – for example, regulatory assets acquired and regulatory liabilities assumed in a business combination.
74
An entity shall provide an explanation of the items described in paragraph 73(f)–(g).
75
For regulatory assets and regulatory liabilities measured in accordance with paragraph 34, an entity shall disclose quantitative information, using time bands, about when it expects to recover the regulatory assets and fulfil the regulatory liabilities. The entity shall disclose the quantitative information disaggregated between:
(a) regulatory assets and regulatory liabilities for which a regulatory agreement applies a regulatory interest rate that is not nil; and
(b) regulatory assets and regulatory liabilities for which a regulatory agreement applies a regulatory interest rate of nil.
76
The entity shall determine the quantitative information required by paragraph 75 using:
(a) undiscounted cash flows, excluding regulatory interest cash flows; and
(b) reasonable and supportable assumptions about the timing of future cash flows that are consistent between periods.
77
The entity shall use its judgement to determine an appropriate number of time bands for the quantitative information required by paragraph 75. For example, an entity might determine appropriate time bands to be:
(a) not later than one year;
(b) later than one year and not later than three years;
(c) later than three years and not later than five years; and
(d) later than five years.
78
For regulatory assets and regulatory liabilities measured in accordance with paragraph 34, an entity shall also disclose:
(a) the discount rate, or ranges of discount rates, used in measuring regulatory assets and regulatory liabilities to which a regulatory agreement applies a regulatory interest rate;
(b) an explanation of how uncertainties affect the recovery of regulatory assets or fulfilment of regulatory liabilities; and
(c) the carrying amounts of regulatory assets and of regulatory liabilities at the end of the reporting period to which the entity has applied the exemption from discounting estimated future cash flows in paragraph 50.
79
For regulatory assets and regulatory liabilities measured by an entity applying paragraph 60, the entity shall provide information about the regulatory assets and regulatory liabilities and the related liabilities and related assets that explains:
(a) the relationship between the carrying amounts, and changes therein, of the regulatory assets or regulatory liabilities and the carrying amounts, and changes therein, of the related liabilities or related assets;
(b) the relationship between the risks associated with the regulatory assets or regulatory liabilities and the risks associated with the related liabilities or related assets; and
(c) how uncertainties affect the recovery of regulatory assets or fulfilment of regulatory liabilities.
80
For example, if a regulatory asset arises from pension costs and is measured by an entity applying paragraph 60, the entity will need to consider how to disclose the information required by this Standard and the information required by AASB 119 Employee Benefits in a manner that shows the relationships described in paragraph 79.
Unrecognised regulatory assets and unrecognised regulatory liabilities
81
An entity shall disclose information about unrecognised regulatory assets and unrecognised regulatory liabilities that enables users of financial statements to understand:
(a) the type of compensation or deduction the unrecognised regulatory assets and unrecognised regulatory liabilities relate to; and
(b) the reason they have not been recognised – for example, an entity might not recognise a regulatory asset because the entity has determined that its regulatory capital base does not have a direct relationship with a related item or items (see paragraph 29).
Relationship between an entity’s regulatory capital base and related items
82
An entity shall disclose information that enables users of financial statements to understand the relationship between the entity’s regulatory capital base and a related item or items. That understanding will:
(a) provide insights into the nature of a regulatory agreement and the effect of a regulatory agreement on the entity’s financial position and financial performance; and
(b) enable users to make comparisons between entities subject to different regulatory agreements.
83
To achieve the objective in paragraph 82, an entity shall disclose:
(a) the type of relationship (direct or not direct) between its regulatory capital base and a related item or items;
(b) the reasons why the entity determined that the relationship is of that type;
(c) any change to or from a direct relationship, and the reason for the change; and
(d) the regulatory approach (nominal or real) used by the regulator to compensate the entity for inflation on its regulatory capital base (see paragraphs B51(a) and B52).
Appendix A -- Defined terms
This appendix is an integral part of the Standard.
allowable expense
A[1]
An item of expense, as defined in Australian Accounting Standards, for which a regulatory agreement provides compensation by adding an amount in determining a regulated rate to be charged by an entity.
allowed revenue
A[2]
The total amount of compensation that a regulatory agreement entitles an entity to charge customers through regulated rates in a period.
chargeable income
A[3]
An item of income, as defined in Australian Accounting Standards, for which a regulatory agreement makes a deduction of an amount in determining a regulated rate to be charged by an entity.
regulated rate
A[4]
A price determined by a regulator that an entity charges for goods or services supplied to customers in a period.
regulator
A[5]
A body that is required by law or regulation to apply a regulatory agreement to determine a regulated rate (or a range for the regulated rate).
regulatory agreement
A[6]
An agreement that creates a set of enforceable rights and enforceable obligations that prescribes how a regulator determines a regulated rate (or a range for the regulated rate).
regulatory asset
A[7]
An enforceable present right, created by a regulatory agreement, to add an amount in determining a regulated rate to be charged to customers in future periods because part or all of the total allowed compensation for regulatory goods or services already supplied has not yet been included in revenue recognised from contracts with customers applying AASB 15.
regulatory capital base
A[8]
Assets and other items that a regulatory agreement entitles an entity to recover by adding an amount for regulatory depreciation in determining a regulated rate to be charged to customers.
regulatory depreciation
A[9]
The systematic allocation by a regulator of an amount of a regulatory capital base to be added in determining a regulated rate.
regulatory expense
A[10]
Expense arising from changes in a regulatory asset or a regulatory liability.
regulatory goods or services
A[11]
Goods or services supplied by an entity to comply with a regulatory agreement.
regulatory income
A[12]
Income arising from changes in a regulatory asset or a regulatory liability.
regulatory interest rate
A[13]
The interest rate specified or implied by a regulatory agreement to provide compensation for the time period until recovery of a regulatory asset or to make a deduction for the time period until fulfilment of a regulatory liability.
regulatory liability
A[14]
An enforceable present obligation, created by a regulatory agreement, to deduct an amount in determining a regulated rate to be charged to customers in future periods because part or all of the total allowed compensation for regulatory goods or services to be supplied in the future has already been included in revenue recognised from contracts with customers applying AASB 15.
regulatory return
A[15]
The return on the regulatory capital base resulting from the rate of return a regulatory agreement applies to a regulatory capital base.
total allowed compensation (for regulatory goods or services)
A[16]
The amount of compensation to which a regulatory agreement entitles an entity for regulatory goods or services supplied in a reporting period. The amount might be charged through regulated rates in either the same period as the entity supplies the regulatory goods or services, or a different period.
Term defined in another Australian Accounting Standard and used in this Standard with the same meaning
customer (defined in AASB 15)
A[17]
A party that has contracted with an entity to obtain goods or services that are an output of the entity’s ordinary activities in exchange for consideration.
Appendix B -- Application guidance
This appendix is an integral part of the Standard. It describes the application of paragraphs 1–83 and has the same authority as the other parts of the Standard.
B1
This appendix provides application guidance on:
(a) enforceable present rights and enforceable present obligations (see paragraphs B2–B10);
(b) differences in timing (see paragraphs B11–B58);
(c) recognition of regulatory assets and regulatory liabilities arising from regulatory depreciation of a regulatory capital base (see paragraphs B59–B72);
(d) the boundary of a regulatory agreement (see paragraphs B73–B87);
(e) uncertain future cash flows (see paragraphs B88–B91);
(f) application of this Standard with Interpretation 12 Service Concession Arrangements (as identified in AASB 1048 Interpretation of Standards) (see paragraphs B92–B94); and
(g) disclosure – aggregation and disaggregation (see paragraphs B95–B97).
Enforceable present rights and enforceable present obligations
B2
This section covers:
(a) assessing enforceability (see paragraphs B3–B7); and
(b) identifying the regulator (see paragraphs B8–B10).
Assessing enforceability
B3
Paragraph 8 requires an entity to assess whether it has an enforceable present right or enforceable present obligation to add or deduct an amount in determining a regulated rate to be charged to customers in future periods.
B4
An entity assesses whether an enforceable present right or enforceable present obligation exists by using judgement and considering all reasonable and supportable information that is available without undue cost or effort. Such information might relate to:
(a) the legal and regulatory framework (see paragraph B5); or
(b) a specific difference in timing (see paragraph B6).
B5
Whether rights and obligations created by a regulatory agreement are enforceable is a matter of law. An enforceable present right or enforceable present obligation need not be explicitly specified in a regulatory agreement. An entity shall consider whether enforceable present rights or enforceable present obligations exist in the context of the applicable legal and regulatory framework that ensures a party’s rights and obligations are upheld. Applicable regulatory decisions or court rulings might provide evidence about the existence of enforceable present rights or enforceable present obligations. The entity shall consider any applicable laws or legal precedents that could supplement or override the terms of the regulatory agreement. Other factors might provide evidence in specific jurisdictions.
B6
Facts or circumstances that might provide evidence of the existence of an enforceable present right or enforceable present obligation in relation to a specific difference in timing include:
(a) confirmation from a regulator of amounts to be added to or deducted from future regulated rates;
(b) explicit requirements or guidelines in a regulatory agreement;
(c) evidence that allowable expenses have been incurred;
(d) direct precedents – an entity’s experience with its regulator’s interpretation of the regulatory agreement in similar circumstances;
(e) indirect precedents – such as (i) the experience of other entities regulated by the same regulator, (ii) the decisions of other regulators in the same jurisdiction or (iii) court rulings in similar circumstances in the same jurisdiction;
(f) preliminary views expressed by a regulator; and
(g) advice from qualified and experienced legal or other advisers.
B7
In assessing whether an enforceable present right or enforceable present obligation exists, an entity shall consider the overall balance of the evidence. The presence of an individual fact or circumstance described in paragraph B6 might not be sufficient to enable an entity to determine whether a regulatory asset or regulatory liability exists. The weight given to each fact or circumstance in the assessment might depend on the legal and regulatory framework within which the entity operates and the effectiveness of the enforcement processes (see paragraph B5).
Identifying the regulator
B8
A regulator is a body that is required by law or regulation to apply a regulatory agreement to determine a regulated rate (or a range for the regulated rate). For a regulatory asset or a regulatory liability to exist, a regulator needs to be a party to the regulatory agreement (see paragraph 9(a)).
B9
Only situations in which a rate is determined by a regulator give rise to regulatory assets or regulatory liabilities. For example, a parent entity might determine the rate that a subsidiary charges its customers for goods or services supplied to them. However, the parent entity is not a body that is required by law or regulation to determine the rate the subsidiary is required to apply in its contracts with customers. Accordingly, the parent entity is not a regulator for the purposes of this Standard and, as a consequence, the agreement between the parent entity and its subsidiary is not a regulatory agreement that can create regulatory assets or regulatory liabilities.
B10
Examples of when regulatory assets or regulatory liabilities might arise include when:
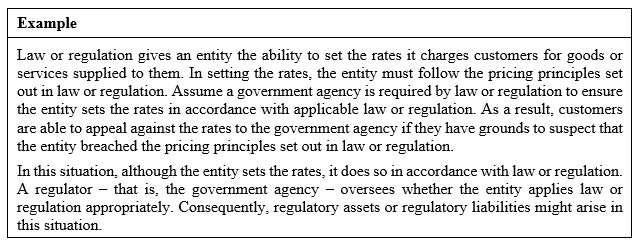
(a) an entity or a related party of the entity sets rates in accordance with a specified legal and regulatory framework and the application of that framework is subject to oversight or approval by a body that is required to do so by law or regulation.
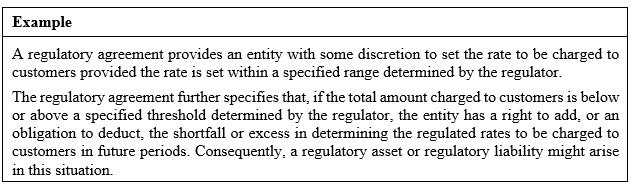
(b) a regulatory agreement permits some flexibility in the rates charged to customers, with an entity being allowed some discretion to set the rate within a range of rates determined by the regulator.
Differences in timing
B11
Paragraph 19 sets out the most common types of compensation provided or deductions made by regulatory agreements. This section describes differences in timing that might arise from such compensation or deductions:
(a) differences in timing arising from compensation for allowable expenses and deductions for chargeable income (see paragraphs B13–B29);
(b) differences in timing arising from a regulatory return on an entity’s regulatory capital base (see paragraphs B30–B40);
(c) differences in timing arising from performance incentives (see paragraphs B41–B50); and
(d) differences in timing arising from compensation relating to inflation (see paragraphs B51–B54).
B12
This section also describes differences in timing that arise from the under-recovery or over-recovery of allowed revenue (see paragraphs B55–B58).
Differences in timing arising from compensation for allowable expenses and deductions for chargeable income
B13
This section describes:
(a) differences in timing arising from compensation for allowable expenses (see paragraphs B14–B19);
(b) differences in timing arising from deductions for chargeable income (see paragraphs B20–B22);
(c) differences in timing arising from compensation or deductions for income taxes (see paragraphs B23–B25); and
(d) the distinction between differences in timing and measurement differences (see paragraphs B26–B29).
Differences in timing arising from compensation for allowable expenses
B14
An allowable expense is an item of expense, as defined in Australian Accounting Standards, for which a regulatory agreement provides compensation by adding an amount in determining a regulated rate to be charged by an entity. The regulatory agreement might determine the compensation for an allowable expense at an amount that differs from the expense recognised by applying Australian Accounting Standards (see paragraphs B26–B29).
B15
As stated in paragraph 19, compensation for an allowable expense forms part of the total allowed compensation for the reporting period in which an entity recognises the allowable expense by applying Australian Accounting Standards. Therefore, a difference in timing arises if the regulator includes compensation for an allowable expense in determining the regulated rates charged in a period that differs from the reporting period in which the entity recognises the allowable expense by applying Australian Accounting Standards.
B16
Compensation for an allowable expense is provided through either regulatory depreciation of an entity’s regulatory capital base or a component of compensation separate from regulatory depreciation.
Compensation for allowable expenses provided through regulatory depreciation
B17
Differences in timing might arise from compensation for allowable expenses provided through regulatory depreciation (see paragraphs B59–B72). For example:
(a) for depreciation or amortisation expense – a difference in timing arises if there is a difference between:
(i) the recovery period or recovery pattern of the items included in the regulatory capital base related to depreciable or amortisable assets; and
(ii) the useful lives or depreciation or amortisation method for those assets determined by applying Australian Accounting Standards; or
(b) for an allowable expense other than depreciation or amortisation expense – a difference in timing arises if an entity recognises an allowable expense in a reporting period by applying Australian Accounting Standards and the compensation for that allowable expense is included in the regulatory capital base, and hence is recovered through regulatory depreciation in future periods.
Compensation for allowable expenses provided separately from regulatory depreciation
B18
Compensation for allowable expenses might be provided through a component of compensation separate from regulatory depreciation. For example, compensation for pension costs, income taxes or provisions is often provided through a separate component of compensation included in the regulated rates.
B19
Examples of differences in timing that arise from compensation provided through a component of compensation separate from regulatory depreciation include:
(a) differences in timing that arise if compensation for an allowable expense is included in determining the regulated rates charged to customers either earlier or later than an entity recognises the allowable expense by applying Australian Accounting Standards. For example:
(i) an entity recognises depreciation expense or amortisation expense as an asset is used to supply regulatory goods or services. However, the regulatory agreement provided compensation for the depreciation expense or amortisation expense in advance, separately from regulatory depreciation (see paragraph B59).
(ii) an entity recognises an allowable expense in a period by applying Australian Accounting Standards. However, the regulatory agreement provides compensation for the allowable expense in determining the regulated rates charged to customers only when an entity settles the related liability in cash, or soon after that (see paragraphs 58 and 60–61).
(iii) an entity recognises expected credit losses in a period by applying AASB 9 Financial Instruments. However, the regulatory agreement provides compensation for such losses in determining the regulated rates charged to customers only when the regulator determines that there is no reasonable expectation of the entity receiving the related cash (see paragraphs 59–61).
(iv) an entity recognises an allowable expense in a period. However, the regulatory agreement provides compensation for that allowable expense by applying another accounting framework used to prepare financial statements. The timing of the compensation determined by applying that accounting framework differs from the timing of the recognition of the allowable expense determined by applying Australian Accounting Standards (see paragraph B29).
(b) differences in timing that arise from differences between the estimated and actual compensation. For example, the regulatory agreement determines compensation for an allowable expense to be added in determining the regulated rates charged to customers based on estimated amounts. However, the regulatory agreement specifies that any difference between the estimated and actual amounts is added or deducted in determining the regulated rates to be charged to customers in future periods.
Differences in timing arising from deductions for chargeable income
B20
Chargeable income is an item of income, as defined in Australian Accounting Standards, for which a regulatory agreement makes a deduction of an amount in determining a regulated rate to be charged by an entity. The regulatory agreement might determine the deduction for chargeable income at an amount that differs from the income recognised by applying Australian Accounting Standards (see paragraphs B26–B29).
B21
As stated in paragraph 19, a deduction for chargeable income reduces the total allowed compensation for the reporting period in which the entity recognises the chargeable income by applying Australian Accounting Standards. Therefore, a difference in timing arises if the entity recognises chargeable income by applying Australian Accounting Standards in a reporting period that differs from the period in which the regulatory agreement makes the deduction for that chargeable income in determining the regulated rates charged to customers.
B22
As with compensation for allowable expenses, deductions for chargeable income are either:
(a) deductions for chargeable income made by reducing regulatory depreciation (see paragraphs B59–B72). For example, an entity’s regulatory capital base might be reduced by a deduction for a gain on disposal of a depreciable asset recognised by applying Australian Accounting Standards. A difference in timing will arise because the deduction will be made in determining the regulated rates charged to customers in future periods.
(b) deductions for chargeable income made separately from regulatory depreciation in determining the regulated rates to be charged to customers. For example, a regulatory agreement might make a deduction in determining the regulated rates for a gain arising from a commodity futures contract. A difference in timing arises if the entity recognises the gain by applying Australian Accounting Standards in a reporting period that differs from the period in which the deduction is made in determining the regulated rates charged to customers.
Differences in timing arising from compensation or deductions for income taxes
B23
An entity recognises tax expense or tax income by applying AASB 112 Income Taxes. Such tax expense or tax income might be an allowable expense or chargeable income. A difference in timing arises if part or all of the compensation or deduction for such tax expense or tax income is included in determining the regulated rates charged to customers in a different period from when the tax expense or income is recognised.
B24
For example, a difference in timing arises if a regulatory agreement provides compensation or makes a deduction in determining the regulated rates charged in a reporting period for current tax expense or income but not for deferred tax expense or income for that period.
B25
An entity shall also apply AASB 112 to account for differences between the carrying amount of a regulatory asset or regulatory liability and its tax base. Applying AASB 112, the entity might recognise a deferred tax liability or deferred tax asset related to a regulatory asset or regulatory liability. Further, the recognition of a deferred tax liability or deferred tax asset – and its related deferred tax expense or deferred tax income – in a reporting period might give rise to another regulatory asset or regulatory liability, which in turn results in the recognition of further deferred tax. In such cases, the measurement of the regulatory asset or regulatory liability related to the deferred tax reflects that iterative process, resulting in an amount for the regulatory asset or regulatory liability that includes the compensation or deduction for its own tax effect.
Measurement differences
B26
In some cases, the total amount of compensation for an allowable expense or a deduction for chargeable income determined by a regulatory agreement over all periods differs from the total amount of the expense or income an entity will recognise over all periods by applying Australian Accounting Standards. Such differences are measurement differences that do not reverse over time.
B27
A measurement difference might arise from compensation for an allowable expense or a deduction for chargeable income without that compensation or deduction giving rise to a difference in timing. For example, a regulatory agreement might determine the compensation for an allowable expense recognised in a reporting period based on an estimate, and not adjust future regulated rates to be charged to customers to reflect any difference between the estimate and the actual expense recognised. Such a difference is a measurement difference, not a difference in timing. The measurement difference is reflected in the statement(s) of financial performance in the reporting period through the recognition of AASB 15 revenue, which includes compensation based on the estimate, and the recognition of the expense for the actual amount.
B28
In other cases, a difference in timing and a measurement difference might occur concurrently. In the example described in paragraph B27, assume that the regulatory agreement specifies that compensation based on an estimate for the allowable expense recognised in a reporting period is added in determining the regulated rates to be charged to customers in the future. A difference in timing – a regulatory asset – arises from the delayed compensation. There is also a measurement difference arising from any difference between the compensation based on the estimate and the actual expense recognised. The future cash flows arising from the regulatory asset – and hence its measurement – are determined by the amount of the compensation, not by the amount of allowable expense recognised by applying Australian Accounting Standards. The measurement difference is reflected in the statement(s) of financial performance in the reporting period through the recognition of regulatory income for the compensation based on the estimate, and the recognition of the expense for the actual amount.
B29
A regulatory agreement might determine compensation for an allowable expense or a deduction for chargeable income for a reporting period by using the related expense or related income that would be recognised in the period by applying an accounting framework other than Australian Accounting Standards. As a result, the amount of compensation or deduction that is included in determining the regulated rates charged in the period might differ from the related expense or related income recognised in that period by applying Australian Accounting Standards. However, such differences are not measurement differences if the total amount of the compensation or deduction over all periods equals the total amount of the expense or income an entity recognises over all periods by applying Australian Accounting Standards. Instead, these differences are differences in timing because part or all of the compensation or deduction for the expense or income the entity recognises in a reporting period is included in determining the regulated rates charged in a different period.
Differences in timing arising from a regulatory return on an entity’s regulatory capital base
B30
Regulatory agreements generally apply a rate of return to an entity’s regulatory capital base for a period, resulting in a regulatory return to which the entity is entitled for the period.
B31
Regulatory agreements might provide regulatory returns on a nominal or a real basis. A nominal regulatory return includes compensation for inflation (see paragraph B51(a)). Regulatory returns might include only a debt return, only an equity return or both a debt and equity return.
B32
A regulatory capital base might include both assets available for use and assets not yet available for use. In some cases:
(a) an entity has separate regulatory capital bases for assets available for use and for assets not yet available for use; and
(b) the rate of return applied to assets available for use differs from the rate of return applied to assets not yet available for use.
B33
Except in the circumstances specified in paragraph B35, a regulatory return forms part of the total allowed compensation for the reporting period in which the regulatory agreement applies the rate of return to a regulatory capital base.
B34
Differences in timing arise if a regulatory agreement includes part or all of a regulatory return in determining the regulated rates charged to customers in a different reporting period from the period in which the agreement applies the rate of return to the regulatory capital base. For example, a regulatory agreement might determine a regulatory return for a period based on an estimate of an entity’s regulatory capital base. A difference in timing arises if the regulatory agreement provides compensation or makes a deduction for differences between the estimated and actual amounts of the regulatory return for the reporting period in determining the regulated rates to be charged to customers in a future period.
A regulatory return on assets not yet available for use in specific circumstances
B35
This section specifies requirements for differences in timing arising from a regulatory return on assets not yet available for use if:
(a) the entity capitalises borrowing costs related to those assets by applying AASB 123 Borrowing Costs;
(b) the regulatory return is only a debt return or both a debt and equity return; and
(c) the entity’s regulatory capital base has a direct relationship with those assets (see paragraphs B59–B72).
B36
In the circumstances described in paragraph B35, the entity shall treat part or all of the regulatory return as compensation for an allowable expense – that is, the capitalised borrowing costs:
(a) if the regulatory return comprises only a debt return, the regulatory return forms part of the total allowed compensation for the reporting periods in which the entity recognises the borrowing costs as an expense, in accordance with paragraph 19 – that is, for the periods in which the assets are available for use; and
(b) if the regulatory return comprises both a debt and equity return, the regulatory return is treated as two parts:
(i) the regulatory return amounting to the entity’s capitalised borrowing costs forms part of the total allowed compensation for the reporting periods in which the entity recognises the borrowing costs as an expense, in accordance with paragraph 19 – that is, for the periods in which the assets are available for use; and
(ii) the regulatory return in excess of the entity’s capitalised borrowing costs forms part of the total allowed compensation for the reporting period in which the regulatory agreement applies the rate of return to the regulatory capital base, in accordance with paragraph B33 – that is, for the periods in which the assets are not yet available for use.
B37
Table B1 provides an overview of the regulatory assets and regulatory liabilities that might arise from differences in timing relating to the regulatory returns described in paragraph B36. The requirements set out in paragraph B66 for the determination of individual differences in timing apply to the differences in timing described in paragraph B36. However, an entity is permitted to determine individual differences in timing described in paragraph B36 using the disaggregation of the capitalised borrowing costs the entity uses to calculate depreciation or amortisation expense related to those costs.
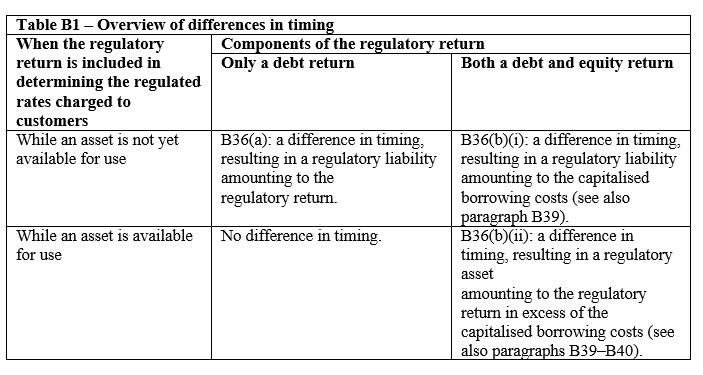
B38
The effect of the differences in timing described in Table B1 in the statement of profit or loss differs because of the different reporting periods in which the regulatory return forms part of total allowed compensation as set out in paragraph B36:
(a) if the regulatory return comprises only a debt return – any difference between the regulatory return and the capitalised borrowing costs is a measurement difference that is recognised in profit or loss in the periods in which the assets are available for use (see paragraphs B26–B29); and
(b) if the regulatory return comprises both a debt and equity return – the regulatory return in excess of the capitalised borrowing costs is recognised in profit or loss in the periods in which the rate of return is applied to the regulatory capital base (that is, the periods in which the assets are not yet available for use).
B39
In some cases, a regulatory return that comprises both a debt and equity return on an asset not yet available for use is determined on a real basis (see paragraph B52). In such cases, an entity shall determine any regulatory asset or regulatory liability that might arise from the regulatory return described in paragraph B36(b) by applying a real interest rate to the inflation‑adjusted borrowings related to the assets not yet available for use.
B40
Applying paragraph 8, an entity is required, during the period in which the asset is not yet available for use, to assess whether it has an enforceable present right for the regulatory return accrued to date to be added in determining the regulated rates to be charged in future periods. To make this assessment for the regulatory assets that arise from the regulatory returns described in paragraph B36(b)(ii), an entity shall consider what rights it would have if the regulator or another party were to terminate the regulatory agreement at the end of the reporting period for a reason other than the entity’s failure to perform as specified in the agreement. The entity shall apply paragraphs B4–B7 to assess whether, in those circumstances, it would have an enforceable present right to receive an amount that reflects the regulatory return accrued to date.
Differences in timing arising from performance incentives
B41
A regulatory agreement might reward or penalise an entity with performance incentives for meeting or failing to meet performance criteria. These criteria could include, for example, targeted levels of service quality, reliability or customer satisfaction. Alternatively, these criteria might relate to an entity’s efficiency in incurring capital and operating expenditure or performance in constructing an item of property, plant or equipment.
B42
Performance incentives form part of the total allowed compensation for the reporting period in which an entity’s performance occurs. To determine that period, the entity shall consider the regulatory agreement’s terms relating to the performance incentives, together with other facts and circumstances.
B43
A difference in timing arises if the period in which a performance incentive is included in determining the regulated rates charged to customers differs from the reporting period in which an entity’s performance occurs.
B44
A regulatory agreement might determine a performance incentive in several ways. For example, a performance incentive might be determined using a fixed monetary amount (such as CU100) or a formula (such as 1% of the amounts charged to customers during a specified period), or by using a rate of return (such as an additional 1%) applied to the regulatory capital base for a specified period. When a performance incentive is determined by using a rate of return, an entity shall account for the performance incentive by applying paragraphs B41–B50, not by applying paragraphs B30–B40 as if it were part of the regulatory return.
Performance incentives relating to an entity’s performance beyond the reporting period
B45
A performance incentive might relate to an entity’s performance over a period that extends beyond the reporting period. In such cases, at the end of the reporting period, applying paragraph 8 an entity shall assess whether it has an enforceable present right to add, or an enforceable present obligation to deduct, an amount that reflects its performance to date in determining the regulated rates to be charged in future periods. The amount that reflects performance to date shall be determined as described in paragraph B47.
B46
To make the assessment required by paragraph 8, an entity shall consider what rights and obligations it would have if the regulator or another party were to terminate the regulatory agreement at the end of the reporting period for reasons other than the entity’s failure to perform as specified in the agreement. The entity shall apply paragraphs B4–B7 to assess whether, in those circumstances, it would have an enforceable present right to receive or an enforceable present obligation to pay an amount that reflects its performance to date.
B47
The entity shall estimate the total amount of the performance incentive using either the most likely amount method or the expected value method in accordance with paragraph 42, and determine the portion of that estimated amount that reflects performance to date using a reasonable and supportable basis.
Performance incentives depending on more than one performance criterion
B48
In some cases, a performance incentive depends on more than one performance criterion and the criteria apply over periods with different end dates. Some amounts of the performance incentive will remain conditional on future performance criteria after other amounts have become unconditional. In such cases, an entity shall assess whether the amounts that remain conditional relate only to an entity’s performance in future periods. For example, assume that a regulatory agreement provides an entity with a bonus of CU1,000 for reaching specified construction milestones but specifies that CU400 of that bonus is conditional on the asset continuing to operate at a specified level of capacity over a specified future period. The entity might assess that the bonus of CU1,000 comprises:
(a) an amount of CU600 that is related to the construction milestones – in which case this amount forms part of the total allowed compensation for the reporting period(s) in which the entity constructs the asset; and
(b) an amount of CU400 that is related to the entity maintaining a specified level of capacity over a specified future period – in which case this amount forms part of the total allowed compensation for the specified future reporting period(s) in which the asset operates at the specified level.
B49
The performance criteria might relate to an entity’s performance beyond the reporting period. For each such performance criterion, an entity shall apply paragraphs B45–B47.
Compensation or deduction for performance incentives through regulatory depreciation
B50
A regulatory agreement might specify that compensation or a deduction for a performance incentive related to an entity’s performance for a period is added to or deducted from the entity’s regulatory capital base. In such cases, differences in timing arise because the compensation or deduction for an entity’s performance for a period is provided or made through regulatory depreciation in future periods (see paragraphs B59–B72).
Differences in timing arising from compensation relating to inflation
B51
Compensation for inflation arising in a reporting period might be provided:
(a) through a nominal regulatory return on a regulatory capital base, to which an entity shall apply paragraphs B30–B40;
(b) by inflation adjustments to a regulatory capital base recovered through regulatory depreciation (see paragraph B52); or
(c) through a component of compensation that is separate from regulatory depreciation (see paragraphs B53–B54).
B52
In some cases, a regulatory agreement applies a real rate of return to a regulatory capital base that is adjusted by inflation. Applying paragraph 20, an entity shall treat compensation provided by these inflation adjustments as forming part of the total allowed compensation for the reporting period in which the inflation is recovered through regulatory depreciation included in determining the regulated rates charged to customers. Accordingly, an entity shall not recognise any amounts for regulatory assets or regulatory liabilities for such compensation.
B53
A regulatory agreement might provide compensation for inflation arising in a reporting period separately from regulatory depreciation. Such compensation forms part of the total allowed compensation in that reporting period.
B54
Differences in timing could arise from such compensation for inflation. For example, a regulatory agreement might provide an entity with compensation for inflation for the current reporting period. That compensation might be based on the expected inflation rate for that period being applied to determine estimated costs or the entity’s allowed revenue for the period. The regulatory agreement might also require the entity to add or deduct differences between the estimated and actual inflation rates for the current reporting period in determining the regulated rates to be charged to customers in future periods. Differences between the estimated and actual inflation rates give rise to a difference in timing in the current reporting period (see paragraph B19(b)).
Differences in timing arising from allowed revenue
B55
Allowed revenue is the total amount of compensation that a regulatory agreement entitles an entity to charge customers through regulated rates in a period. A regulatory agreement typically:
(a) determines an entity’s allowed revenue for a period by considering different types of compensation or deductions, primarily those described in paragraph 19; and
(b) determines the regulated rates for a period by dividing the allowed revenue for the period by the estimated quantity of goods or services to be supplied to customers in that period.
B56
Differences in timing arise from paragraph B55(a) if allowed revenue for a reporting period includes amounts that form part of total allowed compensation in a different period, as discussed in paragraphs B13–B54.
B57
Differences in timing can also arise from paragraph B55(b), if:
(a) the entity charges customers less or more than the allowed revenue for a reporting period because, for example, it supplies less or more goods or services than were estimated when the regulated rate was determined (volume variances); and
(b) the regulator adds the under‑recovered allowed revenue or deducts the over‑recovered allowed revenue for a reporting period in determining the regulated rates to be charged in a future period.
Compensation or deduction for under‑recovery or over‑recovery of allowed revenue through regulatory depreciation
B58
A regulatory agreement might specify that compensation or a deduction for an under‑recovered or over‑recovered amount of allowed revenue for a period is added to or deducted from the entity’s regulatory capital base. In such cases, differences in timing arise because the compensation or deduction for an entity’s under‑recovered or over‑recovered amount of allowed revenue for a reporting period is provided or made through regulatory depreciation in future periods (see paragraphs B59–B72).
Recognition of regulatory assets and regulatory liabilities arising from regulatory depreciation of a regulatory capital base
Scope of requirements in paragraph 29
B59
Paragraph 29 sets a criterion for the recognition of regulatory assets and regulatory liabilities arising from regulatory depreciation of an entity’s regulatory capital base. In some cases, a regulatory agreement provides compensation for amounts that will arise from depreciable or amortisable assets separately from regulatory depreciation. Such compensation reduces the regulatory depreciation that would otherwise be provided. If such separate compensation does not relate specifically to capitalised borrowing costs and is provided while the assets are not yet available for use, an entity shall treat any regulatory liabilities arising from the compensation as arising from regulatory depreciation of an entity’s regulatory capital base for the purposes of paragraph 29.
Relationship between a regulatory capital base and a related item or items
B60
The regulatory capital base comprises assets and other items that a regulatory agreement entitles an entity to recover by adding an amount for regulatory depreciation in determining a regulated rate to be charged to customers. That regulatory depreciation provides compensation or makes a deduction for amounts arising from related items. Examples of related items are:
(a) items recognised by an entity as depreciable or amortisable assets by applying Australian Accounting Standards;
(b) an allowable expense added to, or chargeable income deducted from, the regulatory capital base other than expenses or income arising from the assets described in (a); and
(c) other amounts added to, or deducted from, the regulatory capital base – for example, performance incentives (see paragraph B50) and the under‑recovery or over‑recovery of allowed revenue (see paragraph B58).
B61
The regulatory capital base could comprise parts that have a direct relationship with a related item or items and a part that does not have such a relationship. An entity shall apply paragraphs 30 and B62–B70 to identify whether any part of its regulatory capital base has a direct relationship with a related item or items. To apply these paragraphs and the disclosure requirements in paragraphs 82–83, an entity shall read the references in those paragraphs to the ‘regulatory capital base’ as being to ‘a part of the regulatory capital base’.
B62
When applying paragraph 30, an entity determines whether its regulatory capital base has a direct relationship with a related item or items. In making that determination, the entity shall use its judgement and consider all reasonable and supportable information that is available without undue cost or effort. Such information includes the regulatory methodology underlying the determination of its regulatory capital base, the determination of the regulatory depreciation, and how the regulator monitors whether regulatory depreciation provides compensation or makes a deduction for amounts arising from a related item or items.
B63
Paragraphs B67–B70 set out indicators of whether a regulatory capital base has a direct relationship with a related item or items. These indicators are not exhaustive. An entity might give more weight to some indicators than others in determining whether its regulatory capital base has a direct relationship with a related item or items. Nonetheless, an entity is permitted to presume its regulatory capital base does not have a direct relationship with depreciable or amortisable assets if neither of the indicators described in paragraph B67 are present.
Direct relationship with depreciable or amortisable assets
B64
A depreciable or amortisable asset is an asset that is depreciable or amortisable in accordance with Australian Accounting Standards – for example, AASB 116 Property, Plant and Equipment, AASB 138 Intangible Assets or AASB 16 Leases. An asset class is a group of assets as described in paragraph 37 of AASB 116, paragraph 119 of AASB 138 or paragraph 8 of AASB 16.
B65
Paragraph 30 states that an entity’s regulatory capital base has a direct relationship with a related item or items if the entity is able to track, by amount and reporting period, how regulatory depreciation provides compensation or makes a deduction for the amounts arising from the related item or items. An entity shall determine whether its regulatory capital base has a direct relationship with its depreciable or amortisable assets by considering the smallest aggregation of assets for which the entity is able to do the tracking specified in paragraph 30. The aggregation shall be no larger than an asset class. For example:
(a) if an entity is able to track such compensation or deductions for individual assets – the regulatory capital base has a direct relationship with the individual assets;
(b) if an entity is not able to track such compensation or deductions for individual assets, but can track such compensation or deductions by disaggregating an asset class – the regulatory capital base has a direct relationship with the assets in the disaggregated part of the asset class for which the entity is able to track the compensation or deductions;
(c) if an entity is not able to track such compensation or deductions for any disaggregation of an asset class, but can track such compensation or deductions for the asset class – the regulatory capital base has a direct relationship with the assets in the asset class; and
(d) if an entity is not able to track such compensation or deductions for any asset class – the regulatory capital base does not have a direct relationship with its depreciable or amortisable assets.
B66
An entity shall determine an individual difference in timing as required by paragraph 25 for each aggregation of assets with which the regulatory capital base has a direct relationship.
B67
Indicators that an entity’s regulatory capital base has a direct relationship with its depreciable or amortisable assets include:
(a) the assets or classes in the regulatory capital base are sufficiently similar to the depreciable or amortisable assets or asset classes for the entity to be able to track any differences between assets or classes in the regulatory capital base and the related assets or asset classes; or
(b) the regulator determines an amount of regulatory depreciation to provide compensation for the depreciation or amortisation expense determined by applying Australian Accounting Standards.
B68
Indicators that an entity’s regulatory capital base does not have a direct relationship with its depreciable or amortisable assets include:
(a) the regulator determines the regulatory capital base by using information that differs significantly from information about the entity’s depreciable or amortisable assets accounted for by applying Australian Accounting Standards; or
(b) the regulator determines regulatory depreciation by considering factors unrelated to the depreciation or amortisation of depreciable or amortisable assets.
Direct relationship with related items other than depreciable or amortisable assets
B69
Indicators that an entity’s regulatory capital base has a direct relationship with related items other than depreciable or amortisable assets (see paragraph B60(b)–(c)) include:
(a) the regulatory capital base has a direct relationship with the entity’s depreciable or amortisable assets; or
(b) the regulator monitors how regulatory depreciation provides compensation or makes a deduction for the amounts arising from the related items separately from the rest of the regulatory capital base. For example, the regulatory monitoring might provide the entity with the information necessary to track, by amount and reporting period, how items in the regulatory capital base that relate to allowable expenses arising in a reporting period are recovered through regulatory depreciation.
B70
An indicator that an entity’s regulatory capital base does not have a direct relationship with related items other than depreciable or amortisable assets is that the entity is unable – using a reasonable and supportable basis – to allocate to related items adjustments to the regulatory capital base or regulatory depreciation. This situation might arise if the regulator determines regulatory depreciation by considering the regulatory capital base as a whole.
Reassessment
B71
An entity shall reassess whether its regulatory capital base has a direct relationship with a related item or items:
(a) if facts or circumstances change or new information becomes available – for example, a change in the regulatory agreement; and
(b) if that change or new information could alter that relationship.
B72
If an entity determines that the relationship between its regulatory capital base and a related item or items has:
(a) ceased to be a direct relationship – the entity shall derecognise any affected regulatory assets and regulatory liabilities and recognise any related regulatory expense or regulatory income in accordance with paragraph 33; and
(b) started to be a direct relationship – the entity shall start to recognise any affected regulatory assets and regulatory liabilities in accordance with paragraph 29, and any resulting regulatory income or regulatory expense.
Boundary of a regulatory agreement
B73
Paragraph 35 states that cash flows within the boundary of a regulatory agreement comprise:
(a) cash flows from amounts added or deducted in determining the regulated rates to be charged to customers in future periods (see paragraphs B74–B80); and
(b) cash flows from compensation on termination of the regulatory agreement (see paragraphs B81–B85).
Regulated rates charged to customers in future periods
B74
Cash flows from amounts added or deducted in determining the regulated rates to be charged to customers in the future are within the boundary of a regulatory agreement if an entity has:
(a) an enforceable present right or enforceable present obligation to supply regulatory goods or services at the future date (see paragraphs B75–B78); and
(b) an enforceable present right to recover a regulatory asset, or an enforceable present obligation to fulfil a regulatory liability, through regulated rates to be charged to customers in the future (see paragraphs B79–B80).
Enforceable present right or enforceable present obligation to supply regulatory goods or services
B75
An entity’s enforceable present right or enforceable present obligation to supply regulatory goods or services at a future date might be affected by a right, held by any party, to renew the regulatory agreement or to terminate it. For example, an entity might have an enforceable present right to renew a regulatory agreement. Such a right would give the entity an enforceable present right to supply regulatory goods or services at a future date covered by that renewal if no other party has an enforceable present right to prevent the renewal.
B76
Rights to renew or terminate a regulatory agreement might be explicit or implicit. In assessing whether such a right affects an entity’s enforceable present right or enforceable present obligation to supply regulatory goods or services at a future date, the entity shall disregard a right held by any party if the party has no practical ability to exercise that right in any circumstances.
B77
The holder of a right might have no practical ability to exercise the right if, for example:
(a) the economic consequences of exercising the right are significantly more adverse for the holder than the consequences of not exercising it;
(b) exercising a right held by an entity would lead to that entity being liquidated or ceasing to trade; or
(c) exercising a right held by a regulator would lead to major disruption in the provision of an essential public service.
B78
In some cases, an entity might conclude that it has an enforceable present right or enforceable present obligation to supply regulatory goods or services for an indefinite period. An entity might reach this conclusion if:
(a) the entity operates through a legal and regulatory framework that entitles the entity to supply regulatory goods or services for an indefinite period; or
(b) the entity operates through renewable agreements for which the renewal is viewed as an administrative procedure – for example, renewal occurs unless the agreement is significantly breached and the direct costs of renewal are insignificant.
Enforceable present right to recover a regulatory asset or enforceable present obligation to fulfil a regulatory liability through regulated rates
B79
Paragraph B4(a) requires an entity to consider the features of its legal and regulatory framework when assessing whether it has an enforceable present right to recover a regulatory asset, or an enforceable present obligation to fulfil a regulatory liability, by adding or deducting an amount in determining the regulated rates to be charged to customers. Examples of situations in which the entity might determine that such an enforceable present right or enforceable present obligation exists include when:
(a) the regulatory process for determining the regulated rate is set out in law and guarantees that the entity will recover its costs and earn a return on amounts included in the regulatory capital base; or
(b) the regulator has historically applied a consistent approach to cost recovery in determining the regulated rates and there is no indication of uncertainty about this approach or potential changes in it.
B80
There might be uncertainty about the existence of an enforceable present right to recover a regulatory asset or an enforceable present obligation to fulfil a regulatory liability by adding or deducting an amount in determining the regulated rates to be charged to customers during the life of the regulatory asset or regulatory liability. If such uncertainty exists, cash flows within the boundary of a regulatory agreement are those for which the entity determines it is more likely than not that such a right or obligation exists.
Compensation on termination of a regulatory agreement
B81
The term ‘compensation on termination of a regulatory agreement’ refers to cash flows arising from an enforceable present right to receive compensation relating to regulatory assets that have not yet been recovered or an enforceable present obligation to pay compensation relating to regulatory liabilities that have not yet been fulfilled. Such compensation could arise in a variety of situations (for example, cancellation of a regulatory agreement, non-renewal of a regulatory agreement or termination of a regulatory agreement by mutual consent).
B82
Cash flows from compensation on termination of a regulatory agreement are within the boundary of a regulatory agreement to the extent that an entity has:
(a) an enforceable present right to receive compensation for unrecovered regulatory assets; or
(b) an enforceable present obligation to pay compensation for unfulfilled regulatory liabilities.
B83
In assessing whether such an enforceable present right or enforceable present obligation exists, an entity shall consider what rights and obligations it would have if the regulator or another party were to terminate the regulatory agreement at the end of the reporting period for reasons other than the entity’s failure to perform as specified in the agreement. The entity shall apply paragraphs B4–B7 to assess whether, in those circumstances, it would have an enforceable present right to receive compensation for unrecovered regulatory assets or an enforceable present obligation to pay compensation for unfulfilled regulatory liabilities to date.
B84
There might be uncertainty about the existence of an enforceable present right to receive compensation or an enforceable present obligation to pay compensation on termination of a regulatory agreement. If such uncertainty exists, cash flows within the boundary of the regulatory agreement are those for which the entity determines it is more likely than not that such a right or obligation exists.
Exercise of a termination right
B85
If a termination right has been exercised so that a contractual right to receive cash or an obligation to pay cash has been created, that right or obligation is a financial asset or financial liability. In such cases, an entity shall apply the derecognition requirements in paragraph 32 and recognise and measure the financial asset or financial liability by applying AASB 9, recognising any resulting difference in profit or loss.
Reassessment of and changes in the boundary
B86
At the end of each reporting period, an entity shall reassess the boundary of a regulatory agreement.
B87
If this reassessment changes the cash flows within the boundary of a regulatory agreement, the entity shall update the carrying amount of any affected regulatory assets or regulatory liabilities. Paragraphs 73(f) and 74 require an entity to disclose changes in the carrying amount of a regulatory asset or regulatory liability caused by a change in the boundary of a regulatory agreement, and an explanation for that change in the boundary.
Uncertain future cash flows
B88
Future cash flows arising from a regulatory asset or regulatory liability might be subject to risks that create uncertainty about the amount or timing of those cash flows. Such risks include:
(a) credit risk – the risk that some customers will not pay the amounts charged.
(b) demand risk – the risk that arises from changes between the estimated and actual demand for goods or services an entity supplies to customers in a period. Demand risk might give rise to volume variances (see paragraph B57(a)).
B89
An entity bears a risk to the extent that the regulatory agreement does not compensate the entity for the outcome of an uncertainty. In such cases, an entity shall include the effects of the uncertainty in the range of possible cash flows when estimating the future cash flows arising from a regulatory asset or regulatory liability. For example, if an entity bears credit risk, the credit risk affects the amounts receivable from customers. These amounts include the net amount from the recovery of regulatory assets and from the fulfilment of regulatory liabilities. To avoid overstating the effect of credit risk, the entity shall estimate the uncollectible amounts by considering the net cash flows that are expected to arise in the same period from regulatory assets and regulatory liabilities that are created by the same regulatory agreement. An entity shall allocate the estimate of uncollectible amounts to regulatory assets only.
B90
Customers bear a risk to the extent that a regulatory agreement provides compensation to an entity for the outcome of an uncertainty in determining future regulated rates. In such cases, an entity shall include the effects of the uncertainty and the compensation for the outcome of the uncertainty in the range of possible cash flows when estimating the future cash flows arising from a regulatory asset or regulatory liability.
B91
For example, assume an entity expects to be unable to collect some amounts from customers in a future period but the regulatory agreement provides compensation for such uncollected amounts in a period after they have not been collected. When measuring a regulatory asset, the entity will include in the estimated future cash flows for a period the expectation that some amounts will be uncollected and include the expectation of compensation for such amounts in the estimated cash flows for the later period in which the regulatory agreement provides the compensation.
Applying this Standard with Interpretation 12 Service Concession Arrangements
B92
Interpretation 12 Service Concession Arrangements (as identified in AASB 1048) applies to public-to-private service concession arrangements if the grantor controls or regulates the price at which the operator must provide services, and if other specified conditions are met (see paragraph 5 of Interpretation 12). Service concession arrangements within the scope of Interpretation 12 might create regulatory assets or regulatory liabilities. In such arrangements, the regulator is typically the grantor as described in Interpretation 12. This Standard refers to the grantor as the regulator and the operator as the entity. An entity shall first apply Interpretation 12 and other Australian Accounting Standards to account for rights and obligations arising from such arrangements before applying this Standard to any remaining rights and obligations that meet the definition of a regulatory asset or a regulatory liability.
B93
In service concession arrangements that might create regulatory assets or regulatory liabilities, an entity’s regulatory capital base includes items of infrastructure arising from the construction or upgrade services provided. In this section, the references to ‘assets’ refer to items of infrastructure that arise from the construction or upgrade services, and the references to ‘the regulatory capital base’ refer to a subset of the regulatory capital base that comprises these assets. Applying Interpretation 12, the entity might account for an intangible asset arising from the consideration it receives for those construction or upgrade services. A regulatory asset or regulatory liability might arise from regulatory depreciation of the regulatory capital base, which provides compensation for the amortisation expense of that intangible asset.
B94
In applying this Standard, an entity shall determine whether the regulatory capital base, or a part of the regulatory capital base, has a direct relationship with any intangible asset recognised by applying Interpretation 12 (see paragraphs B59–B72). The entity shall also determine whether a difference in timing arises from the regulatory depreciation. In particular, if the service concession arrangement gives rise to:
(a) only an intangible asset – the entity shall determine whether a difference in timing arises by considering any difference between:
(i) the recovery period or recovery pattern of the assets in the regulatory capital base; and
(ii) the useful life or amortisation method of the intangible asset.
(b) both an intangible asset and a financial asset – a portion of the assets in the regulatory capital base relates to the intangible asset and the remaining portion relates to the financial asset. In such cases, the entity shall determine whether a difference in timing arises by considering any difference between:
(i) the recovery period or recovery pattern of a part of the regulatory capital base – specifically, the portion of the assets in the regulatory capital base that relates to the intangible asset; and
(ii) the useful life or amortisation method of the intangible asset.
Disclosure – Aggregation and disaggregation
B95
Paragraphs 41–43 of AASB 18 Presentation and Disclosure in Financial Statements set out requirements relating to the aggregation and disaggregation of information. In applying these requirements to information about regulatory income, regulatory expense, regulatory assets and regulatory liabilities, an entity shall consider whether to use the same aggregation or disaggregation of such information provided for other purposes – for example, disclosures presented outside the financial statements, such as in regulatory reports.
B96
Examples of characteristics that might be appropriate as a basis to aggregate or disaggregate the information required by this Standard about regulatory income, regulatory expense, regulatory assets and regulatory liabilities include:
(a) type of rate‑regulated activity – for example, electricity distribution, gas distribution, water supply;
(b) geographical location;
(c) type of regulatory agreement – for example, service concession arrangements or contractual licensing agreements;
(d) type of items that the regulatory assets or regulatory liabilities relate to – for example, recovery of input cost variances, performance incentives, recovery of income taxes, recovery of pension costs; and
(e) exposure to substantially different risks or uncertainties.
B97
The appropriate aggregation or disaggregation might differ for different information and will also depend on the disclosure requirement and disclosure objective to which the information contributes.
Appendix C -- Effective date and transition
This appendix is an integral part of the Standard.
Effective date
C1
An entity shall apply this Standard for annual reporting periods beginning on or after 1 January 2029. Earlier application is permitted. If an entity applies this Standard for an earlier period, it shall disclose that fact in the notes.
Transition
C2
For the purposes of the transition requirements in paragraphs C3–C17:
(a) the date of initial application is the beginning of the annual reporting period in which an entity first applies this Standard; and
(b) the transition date is the beginning of the annual reporting period immediately preceding the date of initial application. If an entity presents adjusted comparative information for any earlier periods:
(i) in its annual financial statements – the transition date is the beginning of the earliest adjusted comparative annual reporting period presented (see paragraph C7(a)); or
(ii) in its interim financial statements – the transition date is the beginning of the earliest adjusted cumulative comparative interim reporting period presented (see paragraph C16(a)).
C3
An entity shall apply this Standard to all regulatory assets and all regulatory liabilities either:
(a) retrospectively in accordance with AASB 108 Basis of Preparation of Financial Statements; or
(b) using the modified retrospective approach, as specified in paragraphs C9–C13.
C4
An entity shall also apply paragraphs C6–C8, regardless of whether the entity elects to apply this Standard retrospectively or to use the modified retrospective approach.
C5
At the transition date, an entity shall:
(a) recognise and measure regulatory assets and regulatory liabilities as if the Standard had always been applied;
(b) derecognise all regulatory balances that the entity would not have recognised as regulatory assets or regulatory liabilities if this Standard had always been applied;
(c) recognise any deferred tax effects of the adjustments described in (a)–(b); and
(d) recognise the net amount of the adjustments described in (a)–(c) in opening retained earnings (or other component of equity, as appropriate).
Comparative information
C6
An entity shall:
(a) present adjusted comparative information for the annual reporting period immediately preceding the date of initial application; and
(b) disclose the quantitative information required by paragraph 28(f) of AASB 108 for the annual reporting period immediately preceding the date of initial application.
C7
An entity is permitted, but not required:
(a) to present adjusted comparative information for any earlier periods presented before the beginning of the annual reporting period immediately preceding the date of initial application;
(b) to disclose the quantitative information required by paragraph 28(f) of AASB 108 for the current period or any earlier periods presented as described in (a); or
(c) to disclose the information specified in paragraphs 68–83 of this Standard for any earlier periods presented as described in (a).
C8
If an entity presents in its primary financial statements or discloses in the notes unadjusted comparative information for any earlier periods presented, the entity shall clearly identify the information that has not been adjusted, disclose that it has been prepared on a different basis, and explain that basis.
Transition reliefs – Modified retrospective approach
C9
At the transition date, an entity electing to use the modified retrospective approach may use one or more of the transition reliefs in paragraphs C10–C12.
C10
An entity may elect to apply the requirements for a regulatory return on assets not yet available for use in specific circumstances (see paragraphs B35–B40) only to assets that are not yet available for use at the transition date.
C11
To apply the requirements for an implied regulatory interest rate (see paragraphs 48–50 and 56–57), an entity may elect to disregard any implied regulatory interest rates that would have been derived from the terms of the regulatory agreement before the transition date.
C12
An entity may use hindsight at the transition date in applying the requirements in this Standard. For example, an entity may use hindsight when estimating the cash flows arising from a regulatory asset or a regulatory liability.
C13
An entity electing to use the modified retrospective approach shall:
(a) disclose which of the transition reliefs in paragraphs C10–C12 it has applied; and
(b) describe, if appropriate, how it has applied those transition reliefs.
Interim financial statements
C14
If an entity applies AASB 134 Interim Financial Reporting in preparing condensed interim financial statements in the first year of applying this Standard, the entity shall present in the condensed interim financial statements each heading and subtotal it expects to use in applying the Standard, despite the requirements in paragraph 10 of AASB 134. An entity shall apply the requirements in paragraph 10 of AASB 134 for headings and subtotals in condensed interim financial statements after it has issued its first set of annual financial statements prepared in accordance with this Standard.
C15
If an entity applies AASB 134 in preparing interim financial statements in the first year of applying this Standard, the entity shall:
(a) present adjusted comparative information for the comparative interim period and the cumulative comparative interim period of the immediately preceding financial year; and
(b) disclose in the notes, as part of the information required by paragraph 16A(a) of AASB 134, the amounts previously presented for each line item affected in the financial statements for the comparative interim period and the cumulative comparative interim period of the immediately preceding financial year.
C16
An entity is permitted, but not required:
(a) to present adjusted comparative information for any earlier comparative interim periods and cumulative comparative interim periods presented before the beginning of the immediately preceding financial year; and
(b) to disclose the information described in paragraph C15(b) for:
(i) the current interim period and the cumulative current interim period; or
(ii) any earlier interim periods presented as described in (a).
C17
If an entity presents in its primary financial statements or discloses in the notes unadjusted comparative information for any earlier interim periods presented, the entity shall clearly identify the information that has not been adjusted, disclose that it has been prepared on a different basis, and explain that basis.
Withdrawal of IFRS 14
C18
[Deleted by the AASB]
Withdrawal of AASB pronouncements
AusC18.1
This Standard repeals AASB 14 Regulatory Deferral Accounts issued in June 2014. Despite the repeal, after the time this Standard starts to apply under section 334 of the Corporations Act (either generally or in relation to an individual entity), the repealed Standard continues to apply in relation to any period ending before that time as if the repeal had not occurred.
[Note: When this Standard applies under section 334 of the Corporations Act (either generally or in relation to an individual entity), it supersedes the application of the repealed Standard.]